HDFC Bank Share : Is it really worth Buy/Hold now?
There are times in the stock market when a good company becomes interesting not when everything is going right, but when the market has already priced in much of the disappointment.
HDFC Bank appears to be at one such point today.
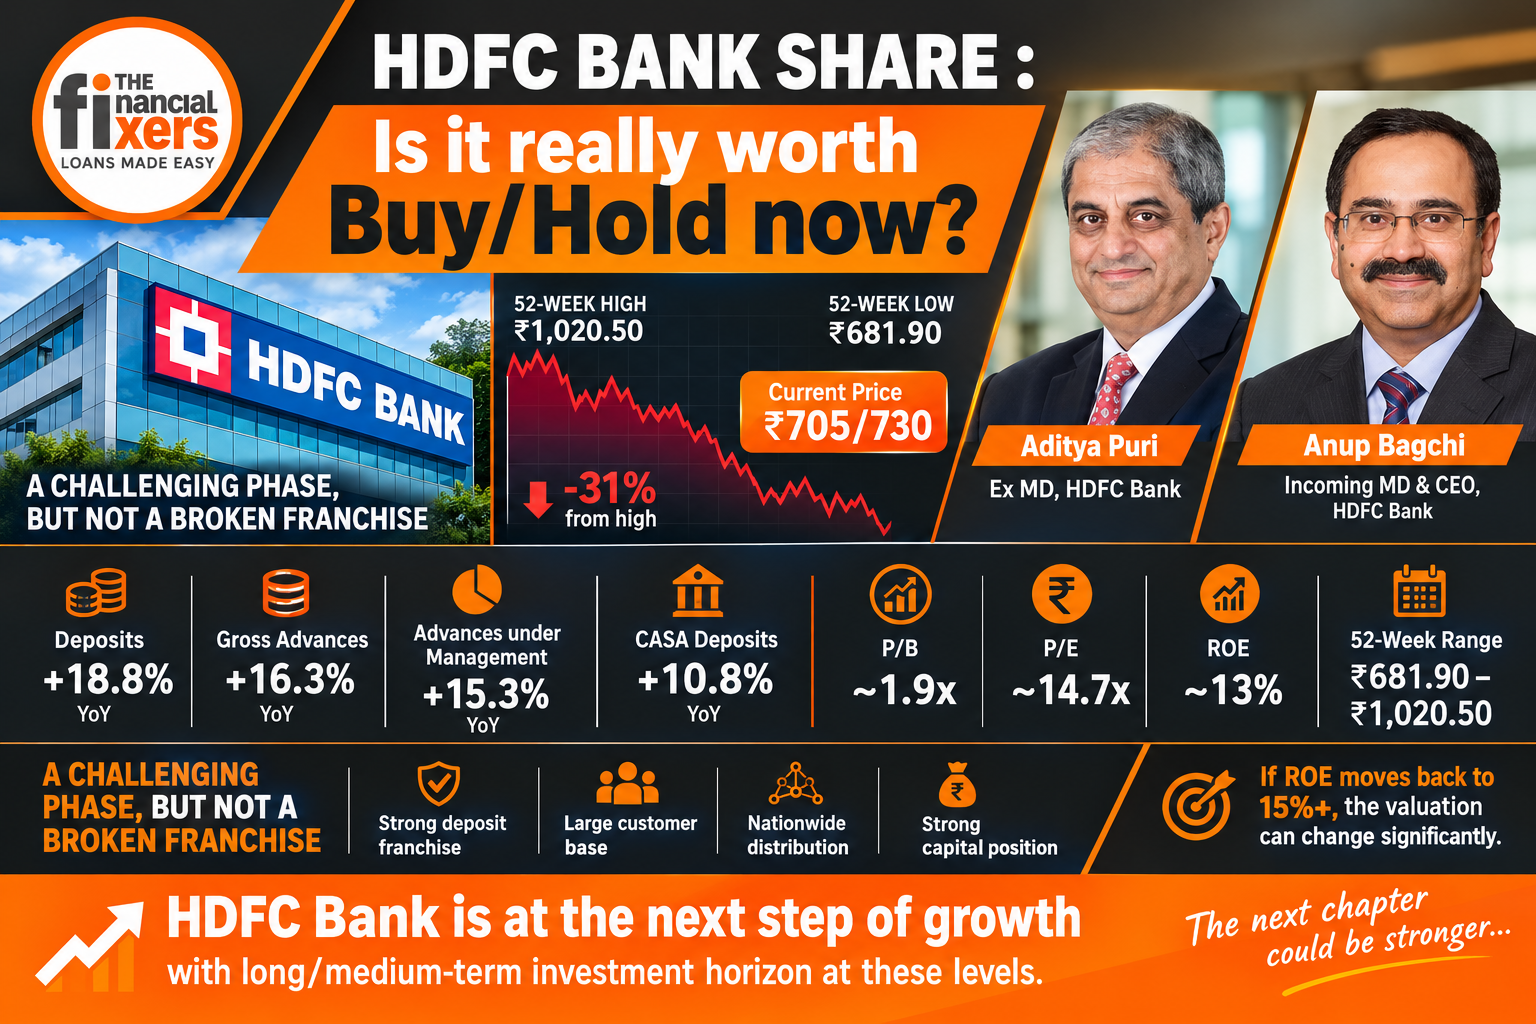
At around ₹705/730, the stock is trading close to its 52-week low of ₹681.90, against a 52-week high of ₹1,020.50. At ₹705, it is almost 31% below its 52-week high. The current P/B is around 1.9x, P/E around 14.7x, and reported ROE is approximately 13%.
For a bank that has historically commanded a much stronger valuation premium, these numbers deserve a closer look.
ROE is the number one would watch most closely
HDFC Bank's current ROE of approximately 13% is clearly below the level at which investors traditionally valued the bank.
But I would not look at this figure in isolation.
The bank has been going through a major transition following the merger with HDFC Ltd., changes in senior management and a period of relatively subdued profitability and margins.
The important question is therefore not whether today's ROE is exceptional.
It isn't.
The question is whether ROE can move back towards the mid-teens as the balance sheet normalises and management execution improves.
That is where the potential investment opportunity lies.
A difficult phase but not a broken franchise
HDFC Bank has undoubtedly faced a challenging period.
There have been regulatory and compliance observations in India and overseas, including matters relating to KYC, outsourcing and other regulatory requirements. The bank's DIFC branch in Dubai also faced restrictions from the DFSA in 2025 concerning regulatory deficiencies.
There have also been earlier technology and operational issues, including the RBI's restrictions on certain credit-card and digital-business activities in 2020.
But I would be careful about portraying these events as evidence of a fundamentally damaged bank.
Issues that a bank of HDFC Bank's size must address and importantly are that can be corrected.
The bank continues to have one of India's largest deposit franchises, an enormous customer base, a nationwide distribution network and substantial capital strength.
For perspective, as of September 2026, HDFC Bank had approximately:
- ₹33.28 lakh crore of deposits, up 18.8% YoY
- ₹32.20 lakh crore of gross advances, up 16.3% YoY
- ₹33.08 lakh crore of period-end advances under management, up 15.3%
- CASA deposits of approximately ₹10.52 lakh crore, up 10.8%.
These are not numbers of a franchise that has lost its ability to grow.
In fact, deposit growth exceeding credit growth is particularly encouraging, because the quality and sustainability of a bank's deposit franchise ultimately determine how comfortably it can grow its loan book.
Aditya Puri
It is impossible to discuss HDFC Bank without acknowledging the extraordinary period under Mr. Aditya Puri.
For almost two decades, HDFC Bank built a reputation for conservative underwriting, strong processes, disciplined growth and consistent execution.
The post-Puri period coincided with the HDFC Ltd. merger, a much larger balance sheet, changing competitive dynamics, technology requirements, regulatory expectations and several changes in senior leadership.
I see the current situation more as a transition phase for one of India's largest financial institutions.
And transitions eventually create opportunities for a reset.
Could Anup Bagchi be reset?
This is where the appointment of Mr. Anup Bagchi becomes particularly important.
Bagchi brings more than three decades of experience across banking, capital markets, wealth management, investment banking, digital financial services and insurance.
He has been part of the ICICI Group since 1992 and has held senior positions including CEO & MD of ICICI Securities, Executive Director of ICICI Bank, and currently MD & CEO of ICICI Prudential Life Insurance.
As Executive Director of ICICI Bank from 2017 to 2023, he handled Retail, Business and Rural Banking, followed by Wholesale Banking.
During his tenure, ICICI Bank became the first private-sector bank to cross a ₹2 lakh crore retail mortgage portfolio.
At ICICI Prudential Life, where he became MD & CEO in 2023, the company crossed ₹10,000 crore of Annualised Premium Equivalent for the first time in FY2025, reaching ₹10,407 crore, while PAT rose nearly 40% to ₹1,189 crore.
These figures demonstrate something important:
Bagchi is not new to running large financial businesses, managing complex organisations or balancing growth with profitability.
His appointment therefore gives HDFC Bank an opportunity to combine its existing franchise strength with a fresh leadership perspective.
Why look at HDFC Bank differently now
The numbers that matter are increasingly moving in the right direction.
Deposits: +18.8%
Gross advances: +16.3%
Advances under management: +15.3%
Current P/B: ~1.9x
Current P/E: ~14.7x
ROE: ~13%
52-week range: ₹681.90–₹1,020.50.
The stock has already suffered a substantial correction from its 52-week high.
At the same time, the underlying franchise continues to grow at a healthy pace.
That combination is interesting.
If the new management can improve operating efficiency, restore confidence, maintain asset quality and gradually take ROE back towards the 15%+ zone, the valuation mathematics can change considerably.
The market does not need HDFC Bank to become a different bank.
It simply needs to see the old strengths working efficiently again within the much larger post-merger organisation.
Realistic View
It is India's largest private-sector bank.
There will certainly be volatility. The stock may not move in a straight line, and the market will demand evidence from the new management.
But at current valuations, I believe the risk-reward has become considerably more interesting than it was when the stock was trading near ₹1,000.
The Investment thesis is simple:
The past few years have tested HDFC Bank.
The next few years may test what HDFC Bank can become again.
And if the bank successfully restores its execution and ROE, the current weakness in the share price could ultimately prove to have been an opportunity rather than a reflection of the bank's long-term franchise value.
HDFC Bank is at next step of growth with long/medium-term investment horizon at these levels.
Disclaimer: This article is only for educational purpose and not a recommendation.